Real estate investment analysis often gravitates toward a single number: yield. It’s an intuitive, easily comparable metric, annual income divided by asset value, and it dominates how many investors initially screen opportunities. But yield, on its own, tells an incomplete story, particularly for investors and developers thinking in decades rather than quarters. Evaluating a portfolio like that associated with Apavou Mauritius, spanning residential, retail, and mixed-use assets, requires looking well beyond this single metric.
The limits of yield as a standalone measure
Yield measures current income relative to current value, but it says nothing about the trajectory of either variable. A property with a modest current yield but strong prospects for rental growth, driven by improving location fundamentals or increasing scarcity of comparable stock, may ultimately outperform a higher-yielding asset in a stagnant or declining submarket. This distinction matters most for investors underwriting a holding period measured in decades rather than years, since it is precisely over that longer horizon that trajectory tends to dominate any advantage captured by a marginally higher starting yield.
This is particularly relevant in Mauritius, where land scarcity means that well-located assets, even those with currently modest yields, often benefit from structural appreciation as surrounding development matures and available land for competing projects diminishes. A purely yield-focused screening approach risks systematically undervaluing exactly the kind of scarce, well-located assets that tend to perform best over multi-decade holding periods.
Location quality and its compounding effects
Location quality is one of the more difficult factors to price accurately, precisely because its value compounds gradually rather than manifesting immediately in current income figures. A property in a location that is well-positioned relative to future infrastructure investment, population growth, or economic development may show relatively unremarkable current performance while quietly building toward substantially higher value in the future.
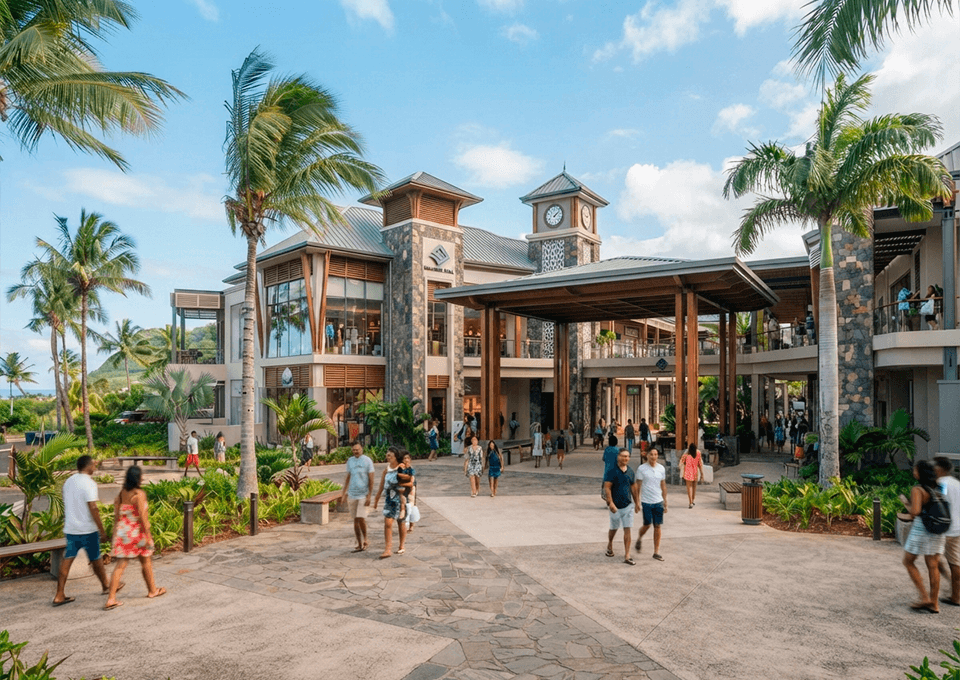
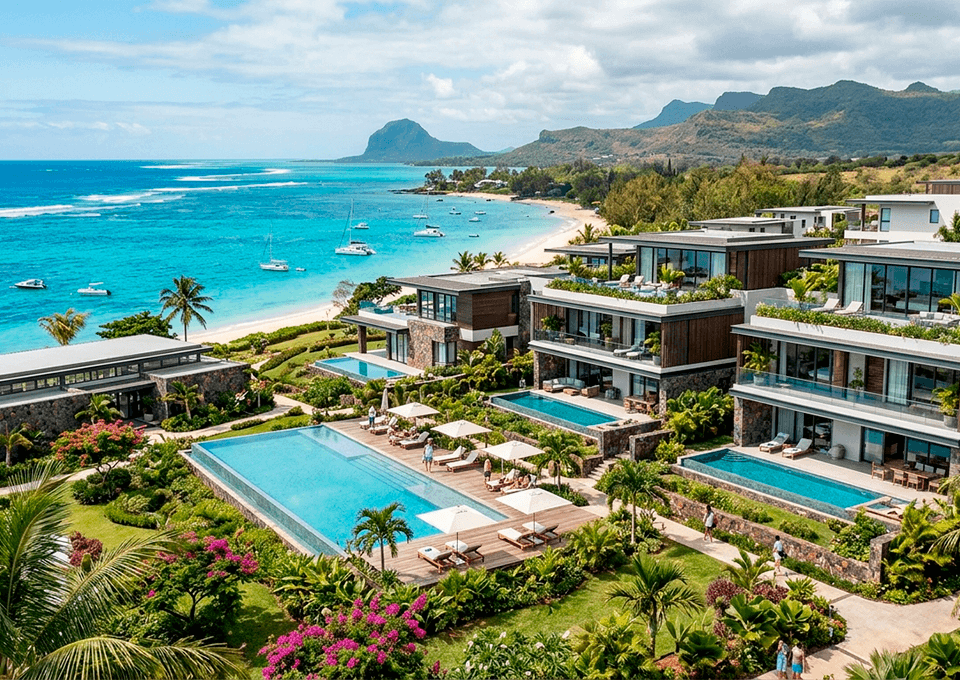
Evaluating a portfolio spanning developments like Terre d’été (residential), Plaisance Mall (retail), and The Cube (mixed-use) requires assessing not just their current performance, but the trajectory of the areas in which they’re located, infrastructure plans, demographic trends, and the broader direction of urban development in the surrounding areas.
The hidden costs that erode returns
Beyond headline income and value figures, a range of less visible costs can meaningfully erode actual returns over time: ongoing maintenance and capital reinvestment requirements, property management costs, vacancy periods between tenancies, and the transaction costs associated with periodic releasing or resale. Properties that appear attractive on a simple yield basis can underperform substantially once these hidden costs are properly accounted for.
This is particularly relevant for older or lower-quality assets, where deferred maintenance can accumulate into significant capital requirements that aren’t reflected in current income figures. Evaluating long-term value requires factoring in a realistic reinvestment reserve, rather than assuming current net income can be extracted indefinitely without ongoing capital support.
Asset quality versus acquisition price
There’s a persistent temptation in real estate investing to prioritise acquisition price, buying cheaply, over underlying asset quality. But quality tends to matter more over long holding periods than initial price. A high-quality asset acquired at a fair price will typically outperform a lower-quality asset acquired cheaply, once the full lifecycle costs of maintenance, tenant turnover, and eventual repositioning are accounted for.
This principle underlies much of the long-term value proposition in developments built with a patrimonial mindset, where material quality, architectural coherence, and thoughtful amenity provision are prioritised even if they increase initial construction costs, because they reduce lifecycle costs and support stronger long-term value retention.
Freehold versus leasehold considerations
Ownership structure represents another dimension often underweighted in simple yield analysis. Freehold ownership provides full long-term control and captures the entire trajectory of land value appreciation, while leasehold structures, common in certain segments of the Mauritian property market, particularly linked to specific residency or investment schemes, carry different long-term value dynamics, including the eventual expiration or renewal terms of the underlying lease.
Long-term investors need to factor these structural differences into their evaluation, since two properties with identical current yields can have meaningfully different long-term value trajectories depending on their underlying ownership structure.
Diversification across asset types and its effect on portfolio value
A portfolio spanning residential, retail, and mixed-use assets, as is the case with Apavou Mauritius’s holdings, benefits from diversification effects that aren’t visible when evaluating individual assets in isolation. Different asset types respond differently to the same macroeconomic conditions: retail performance correlates closely with consumer spending and tourism, residential demand responds more to demographic and employment trends, and mixed-use assets sit somewhere between the two, depending on their specific tenant composition.
This diversification can smooth overall portfolio returns across different phases of the economic cycle, even if individual assets experience more volatile performance in isolation, a benefit that a simple asset-by-asset yield analysis fails to capture.
Scenario planning for different macroeconomic environments
Sophisticated long-term value evaluation involves stress-testing a portfolio against a range of plausible future scenarios, a prolonged tourism downturn, a period of elevated interest rates affecting refinancing conditions, or accelerated inflation in construction and maintenance costs. Rather than relying on a single base-case projection, this scenario-based approach helps identify which assets in a portfolio are genuinely resilient across a range of outcomes, and which are more narrowly dependent on a specific set of favourable conditions persisting.
For a diversified portfolio spanning residential, retail, and mixed-use assets, this kind of scenario planning often reveals that different components of the portfolio provide resilience against different specific risks. Residential assets typically prove more resilient to tourism-specific shocks, for instance, while well-located retail and mixed-use assets may prove more resilient to purely domestic economic slowdowns if they retain meaningful international visitor footfall.
Evaluating management quality as a value driver
Finally, the quality of ongoing management, how actively a portfolio is monitored, how proactively maintenance and repositioning decisions are made, how skillfully tenant relationships are managed, represents a durable driver of long-term value that doesn’t show up directly in any single financial metric, but manifests over time in retention rates, vacancy levels, and the pace of rental growth relative to comparable assets under less attentive management.
The compounding effect of reinvestment discipline
Long-term property value isn’t created purely by holding an asset passively; it depends significantly on how consistently income is reinvested back into the asset over time. Owners who treat all net income as distributable cash, without setting aside adequate reserves for periodic capital improvements, often see their assets gradually fall behind newer competing developments in terms of physical condition and tenant appeal. Conversely, owners who maintain disciplined reinvestment, refreshing common areas, upgrading building systems, and periodically repositioning tenant mix, tend to see their assets command a premium over time relative to comparably located but less well-maintained competitors.
This reinvestment discipline compounds in much the same way that financial returns compound: small, consistent improvements sustained over many years produce a materially different outcome than sporadic, reactive capital spending triggered only once visible deterioration has already affected tenant or resident satisfaction.
Benchmarking against regional alternatives
Investors evaluating a Mauritius-focused portfolio increasingly do so with an eye toward regional alternatives, comparing expected returns, risk profiles, and liquidity characteristics against opportunities in Seychelles, the Maldives, or mainland African markets. This comparative lens matters because it affects the required rate of return investors expect from Mauritian assets: if regional alternatives offer comparable risk-adjusted returns with greater liquidity, Mauritian assets need to offer some combination of higher yield, stronger appreciation potential, or other compensating advantages, such as Mauritius’s more established legal framework and residency-linked investment schemes, to remain competitive for international capital.
The importance of exit optionality
Finally, long-term value evaluation should account for exit optionality, the range of ways an asset could eventually be monetised, whether through outright sale, partial recapitalisation, or generational transfer within a family-owned structure. Assets with a narrower set of realistic exit paths (for instance, a highly specialised property with a limited pool of potential buyers) carry an illiquidity discount that should be factored into any long-term value assessment, even if current income performance appears strong.
Aligning valuation methodology with holding intent
Finally, it’s worth noting that the appropriate valuation methodology itself depends on holding intent. An investor planning to sell within a short window should weigh current market comparables and yield metrics more heavily, since that’s how the asset will likely be priced at the point of sale. A long-term holder, by contrast, should weight structural factors, location trajectory, asset quality, and reinvestment discipline more heavily, since these are the factors that will determine actual realised performance over a multi-decade holding period, even if they don’t fully show up in a simple current-yield snapshot.
Mismatching valuation methodology to actual holding intent is a common source of poor decision-making in real estate, either underinvesting in an asset intended for long-term holding because it was evaluated using short-term metrics, or overpaying for an asset intended for quick resale based on long-term value assumptions that won’t be realised within the actual holding period.
The value of patience in realising long-term appreciation
Long-term property value creation ultimately rewards the patience to hold well-selected assets through multiple market cycles rather than reacting to every short-term fluctuation in sentiment or pricing. This doesn’t mean holding indefinitely regardless of changing fundamentals; genuine structural shifts do sometimes warrant repositioning or disposal, but it does mean resisting the temptation to treat every temporary dip or spike as a signal requiring immediate action. Investors who develop the discipline to distinguish between temporary volatility and genuine structural change tend to capture a meaningfully larger share of an asset’s long-term value creation than those who trade more reactively based on short-term market movements.
Bringing the full picture together
None of these factors, location trajectory, hidden costs, asset quality, ownership structure, diversification, management quality, scenario resilience, or valuation methodology, is sufficient on its own to determine long-term value. It’s the combination and interaction of these factors, assessed together rather than in isolation, that provides a genuinely reliable picture of how a portfolio like Apavou Mauritius’s holdings is likely to perform not just over the next reporting period, but across the multi-decade horizon that long-term real estate investment ultimately requires.
Conclusion
Evaluating a portfolio like Apavou Mauritius’s holdings requires moving well beyond current yield to consider location trajectory, hidden lifecycle costs, asset quality relative to acquisition price, ownership structure, diversification benefits, management quality, scenario resilience, and the patience to hold well-selected assets through full market cycles. Together, these factors provide a far more complete picture of long-term value than yield alone, and they explain why sophisticated, long-horizon investors consistently look past headline yield figures when evaluating real estate opportunities in a market like Mauritius.
 Previous Post

 123 456 7890
 help@sitename.com
 44 Broklyn Street, USA